How can a contractor appear profitable while one project is quietly moving over budget? And how can a restaurant report strong sales while one of its best-selling dishes produces a weak margin? In both cases, revenue and expenses tell only part of the story.
Construction accounting basics revolve around the project, contract, budget, and work performed over time. Restaurant accounting works differently: sales need to connect with recipes, ingredients, stock movement, waste, shifts, and sales channels.
This guide compares both cycles and shows what the accounting system needs to capture in each.
Explore Microtec and see how a connected ERP can give you clearer control over project costs, food cost, inventory, and profitability.
Why Construction Accounting Does Not Fit a Standard Ledger
Construction companies do not operate around a simple daily sale. A single contract can run for months or years while materials, labor, equipment, subcontractors, payments, claims, retention, and contract variations move through the project at different times.
A general ledger can show how much the company spent on materials or labor, but that information has limited management value if it does not show which project consumed the cost.
A contractor may report SAR 10 million in total revenue while one project is profitable, another is approaching its budget limit, and a third is already losing margin. The company-level accounts can still look healthy because the stronger project hides the weaker one.
For this reason, construction accounting needs to connect each relevant transaction with the project, cost category, and stage of work behind it.
Long Contracts: Why a General Journal Is Not Enough
Consider a contractor running three projects at the same time. One has reached finishing work, another is still in structural works, and the third has only recently started.
If cement, labor, equipment, subcontractor costs, and site expenses are recorded only in general accounts, finance may know the company’s total spending but not the cost of each contract.
A useful project accounting structure should be able to follow:
- original contract value;
- approved variations;
- project budget;
- material costs;
- direct labor;
- equipment costs;
- subcontractors;
- site expenses;
- indirect costs where allocated;
- progress claims;
- collections;
- retention;
- committed costs;
- estimated cost to complete.
Microtec’s ERP system includes project management and cost tracking for the real estate and contracting sector alongside finance, purchasing, and inventory. The value of this structure is that project costs can remain connected to the wider financial cycle rather than being rebuilt later in spreadsheets.
When Cash Collected Makes a Project Look More Profitable Than It Is
One of the easiest mistakes in construction is to judge project profitability from the difference between cash received and cash paid.
Suppose a contract is worth SAR 2 million. The contractor has collected SAR 800,000 and recorded SAR 500,000 in costs. Looking only at cash movements, the project appears to have generated a positive difference of SAR 300,000.
That does not necessarily mean the project has earned SAR 300,000 in profit.
The work completed may be behind plan. Supplier invoices may not yet have arrived. Labor may already have consumed most of its budget, while the related work is only halfway complete. There may also be subcontractor commitments or expected rework that has not reached the ledger yet.
Construction management therefore needs to distinguish between:
- recognized revenue
- progress claims
- customer collections
- recorded costs
- committed or unbilled costs
- cash flow
- forecast project margin.
Each number answers a different question.
Construction Accounting Basics: Progress Claims and Project Progress
Progress claims, customer invoices, collections, and accounting revenue often move together, but they are not interchangeable.
A contractor may submit a claim based on certified work, receive payment later, and recognize revenue according to the accounting treatment that applies to the contract. Treating all three amounts as the same figure can distort both project reporting and financial statements.
How Project Progress Affects Revenue Recognition
Under IFRS 15 Revenue from Contracts with Customers, revenue is recognized when a performance obligation is satisfied. A performance obligation can be satisfied at a point in time or over time, depending on the contract and the conditions in the standard.
When a performance obligation is satisfied over time, the company uses an appropriate method to measure progress. IFRS 15 permits both input and output methods, provided the method faithfully reflects the transfer of goods or services to the customer.
This means a construction contract does not automatically use percentage of completion simply because it is a long-term project.
Where a cost-based input method is appropriate, a simplified measure may look like:
Project progress = eligible costs reflecting performance to date ÷ total estimated eligible costs
Suppose a project has a contract value of SAR 5 million and expected costs of SAR 4 million. If SAR 1.2 million of costs appropriately reflects performance completed to date, the simplified progress measure would be 30%.
The calculation still needs professional judgment. Not every amount paid or purchased automatically reflects progress, and IFRS 15 requires the measure to depict the company’s performance in satisfying the relevant obligation.
For project reporting, keep these three figures separate:
| Figure | What it tells you |
| Measure of progress | How far the relevant performance obligation has progressed under the chosen method |
| Progress claim | The amount claimed or certified according to the contract and project process |
| Cash collection | The amount actually received from the customer |
Differences between them are not automatically accounting errors.
Progress Claims, Retention and Subcontractor Costs
Progress claims sit at the center of many construction receivable cycles. A project may move from measuring completed work to certification, invoicing, deductions, retention, collection, and later release of withheld amounts.
A useful system should allow finance to distinguish between:
- current work claimed;
- previous claims;
- advance payments and recovery;
- contractual deductions;
- previous collections;
- retention amounts;
- net amount due;
- applicable VAT;
- customer balance.
Saudi Arabia also has sector-specific VAT considerations. ZATCA’s guidance for the contracting sector covers construction services, real-estate-related services, tax due dates, and invoice timing, including specific considerations for contracts with government entities.
Retention deserves separate tracking as well. A customer may withhold part of a contractor’s entitlement until completion, correction of defects, or another contractual condition is satisfied.
That amount should not disappear inside the general customer balance. Management should be able to identify the original claim, amount retained, amount released, remaining balance, and relevant contractual condition.
Retention also should not automatically be treated as a loss or confused with cash collection. Accounting recognition, contractual entitlement, and VAT timing need to be considered according to the applicable contract and rules.
Also Read: Accounting Software in Saudi Arabia: Types Compared & How to Choose
Construction vs Restaurant Accounting: The Cycle Compared
The biggest difference between the two sectors is the economic unit being managed.
| Cycle element | Construction companies | Restaurants and cafés |
| Primary unit | Project, contract, or work package | Menu item, recipe, branch, or shift |
| Revenue | Based on contract terms and applicable revenue-recognition requirements | Usually generated through individual sales transactions |
| Major costs | Materials, labor, equipment, subcontractors | Ingredients, kitchen labor, packaging, operating costs |
| Inventory | Project materials and stock linked to sites | Fast-moving and often perishable ingredients |
| Main leakage | Overruns, rework, quantity differences, unplanned costs | Waste, spoilage, over-portioning, over-preparation |
| Cycle length | Months or years | Daily operations and recurring shifts |
| Key report | Project cost and margin against budget | Item cost and margin against selling price |
| Collections | Claims, contractual payments, and customer terms | Cash, cards, digital payments, and delivery platforms |
| Tax workflow | Linked to contract, invoicing, and applicable tax-point rules | Linked to taxable sales and daily invoicing |
The financial engine may be the same ledger, but the operational data feeding it is completely different.
If you are still deciding whether your business needs standalone accounting software or a broader ERP structure, see our guide to accounting software in Saudi Arabia.
Restaurant Accounting Basics: From Sale to Plate Cost
Construction accounting starts with the project. Restaurant accounting basics start much closer to the item sold: the recipe, ingredients, sales channel, branch, and shift.
A restaurant can sell 500 meals in a day and produce impressive revenue while still missing its target margin. Sales alone do not reveal whether portions are too large, ingredient prices have increased, waste is rising, discounts are excessive, or delivery commissions are eroding profitability.
Useful restaurant accounting therefore connects the sale to inventory and food cost, rather than recording revenue and investigating cost later.
From Purchases to Portion Cost
Take a dish that includes 180 grams of protein, bread, vegetables, sauce, fries, and delivery packaging.
If the system only knows that the dish sells for SAR 45, management knows the selling price but not what it costs to produce.
A better process begins with a standard recipe or bill of ingredients. Each ingredient has a planned quantity, and current purchase or inventory costs are used to estimate the direct cost of the dish.
A simplified example might look like this:
| Ingredient | Quantity | Approximate cost |
| Protein | 180 g | SAR 7.20 |
| Bread | 1 portion | SAR 1.30 |
| Vegetables and sauce | Recipe quantity | SAR 2.10 |
| Fries | Recipe quantity | SAR 1.80 |
| Packaging | 1 set | SAR 1.50 |
| Direct food and packaging cost | SAR 13.90 |
SAR 13.90 is not necessarily the full accounting cost of serving that dish. Labor, rent, utilities, platform commissions, and other operating costs may still need to be considered.
What the recipe calculation gives management is a cost baseline. Without it, a restaurant can see sales volume but cannot properly investigate whether the item is delivering the expected margin.
Microtec’s O-RED restaurant POS connects restaurant orders and payments with ERP functions for inventory, sales, and cost management.
Where Waste Appears in Restaurant Accounting
Suppose the standard recipe says that 100 portions should consume 18 kilograms of a particular ingredient, but inventory shows that 23 kilograms actually left stock.
The five-kilogram difference needs an explanation.
Possible causes include:
- larger portions than the recipe;
- excess preparation;
- spoilage;
- receiving errors;
- staff meals;
- unrecorded complimentary meals;
- returns;
- canceled orders after preparation;
- inaccurate recipes;
- stock-count errors.
This is why food-cost accounting cannot stop at calculating a theoretical recipe cost. Management needs to compare theoretical consumption with actual stock movement and then investigate the variance.
O-RED connects restaurant order processing with inventory and ERP data, which allows operational activity to feed a wider sales, stock, and cost-management cycle rather than remaining isolated at the cashier.
14 Checks Before Closing a Restaurant Shift
A good close involves more than printing the sales total. Before approving a day or shift, review the operational events that can change the accounting result.
- Recorded sales: Are dine-in, takeaway, and delivery orders complete?
- Payment methods: Are cash, cards, and digital payments classified correctly?
- Cash drawer: Does actual cash match the expected amount?
- Cancellations: Who canceled each order and why?
- Discounts: Were they applied under the correct permissions?
- Complimentary items: Were staff meals and complimentary orders recorded?
- Returns: Did the system capture their effect correctly?
- Ingredient usage: Is stock consumption reasonable for the volume sold?
- Waste: Was spoilage and excess preparation recorded?
- Purchasing: Were received goods entered with the correct quantities and costs?
- Delivery platforms: Do recorded orders match external channel data?
- Commissions: Are delivery fees separated from restaurant revenue?
- VAT: Are taxable sales and VAT recorded correctly?
- Shift close: Were any differences explained before the next shift?
If accounting needs to rebuild all of this each morning from the cashier report, spreadsheets, kitchen notes, and delivery portals, the problem is not simply closing speed. The underlying restaurant cycle is fragmented.
Delivery Commissions and VAT on Restaurant Revenue
Restaurant accounting in Saudi Arabia becomes more complicated when delivery platforms sit between the customer and the restaurant.
Suppose customers generate SAR 20,000 in sales through a platform, but the platform transfers a smaller amount to the restaurant after deducting commissions, service charges, or other adjustments. The bank settlement should not automatically be treated as the restaurant’s sales figure.
Finance needs to distinguish between:
- gross restaurant sales;
- output VAT;
- amount receivable from the platform;
- platform commissions;
- service fees;
- restaurant-funded discounts;
- platform-funded discounts;
- cash ultimately transferred.
The exact accounting and VAT treatment depends on the commercial arrangement, supporting invoices, and nature of each charge.
Saudi Arabia’s current standard VAT rate is 15% where applicable, and VAT-registered businesses are required to account for VAT on taxable supplies under the applicable rules. ZATCA’s current VAT guidance confirms the 15% standard rate.
The important accounting principle is to avoid using the net bank deposit as a shortcut for determining sales revenue.
What Is the Real Difference Between Construction and Restaurant Accounting?
The easiest way to understand the difference is to ask one question: Which unit must I understand before I can understand profitability?
For a contractor, the answer is usually the project or contract. Material, labor, equipment, subcontractor, site expense, claims, and collections need to reach the correct project.
For a restaurant, the answer begins with the item and recipe, then expands to branch, shift, inventory, waste, and sales channel.
Both businesses may use the same general accounting principles, but a chart of accounts alone does not create a useful operating cycle. The accounting system needs the right operational data behind each number.
Read as well: Accounting Services in Saudi Arabia: How to Choose the Right Firm in 2026
What Should Construction Accounting Track in Saudi Arabia?
Construction companies in Saudi Arabia need to consider project accounting, invoicing, VAT, and collections as parts of the same cycle rather than separate finance tasks.
ZATCA’s contracting-sector guidance specifically addresses construction services and VAT issues including tax due dates and invoice timing, while special timing rules can apply to qualifying contracts with government entities.
A practical project record may need to bring together:
- contract details;
- customer;
- original budget;
- progress claims;
- tax invoices;
- collections;
- supplier bills;
- subcontractor costs;
- project expenses;
- retention;
- variations;
- purchase commitments;
- tax-related transaction data.
Simply creating a cost center called Project A is not enough if claims, purchases, stock issues, subcontractors, and collections still sit in disconnected processes.
How to Test a Construction Accounting System
Instead of beginning with a long feature list, run one project from start to finish inside the proposed system.
Create:
- a contract value;
- project budget;
- project cost center;
- material purchase;
- material issue to site;
- labor cost;
- subcontractor invoice;
- site expense;
- progress claim;
- retention;
- customer payment;
- contract variation.
Then ask the system for:
- project cost to date;
- budget versus actual;
- progress claims;
- collections;
- outstanding customer balance;
- supplier and subcontractor exposure;
- remaining project cost estimate;
- project profitability.
If you still need several spreadsheets to understand where the project stands financially, the system has not solved the core construction problem.
If your business also uses an external accountant, reviewer, or audit firm, our guide to accounting services in Saudi Arabia explains how to choose the appropriate provider and verify the required professional scope.
How to Test a Restaurant Accounting System
For a restaurant, test one operating day rather than one project.
Create several menu items and recipes, receive ingredient purchases, process dine-in and delivery orders, apply a discount, record an order cancellation and waste, close a shift, and perform a quick stock count.
Then ask:
- How much did we sell?
- What was the theoretical food cost?
- What ingredient quantity should have been consumed?
- What quantity actually moved out of stock?
- Where was waste recorded?
- How did dine-in and delivery sales differ?
- How much cash was collected?
- What remains receivable from platforms?
- Which items sold the most?
- Which items have weak or deteriorating margins?
If the POS, inventory, and accounting data remain disconnected, restaurant costing will still need to be reconstructed after operations end.
Microtec: Different Workflows for Contractors and Restaurants
Contractors and restaurants should not be forced into the same operational workflow simply because both ultimately produce accounting entries.
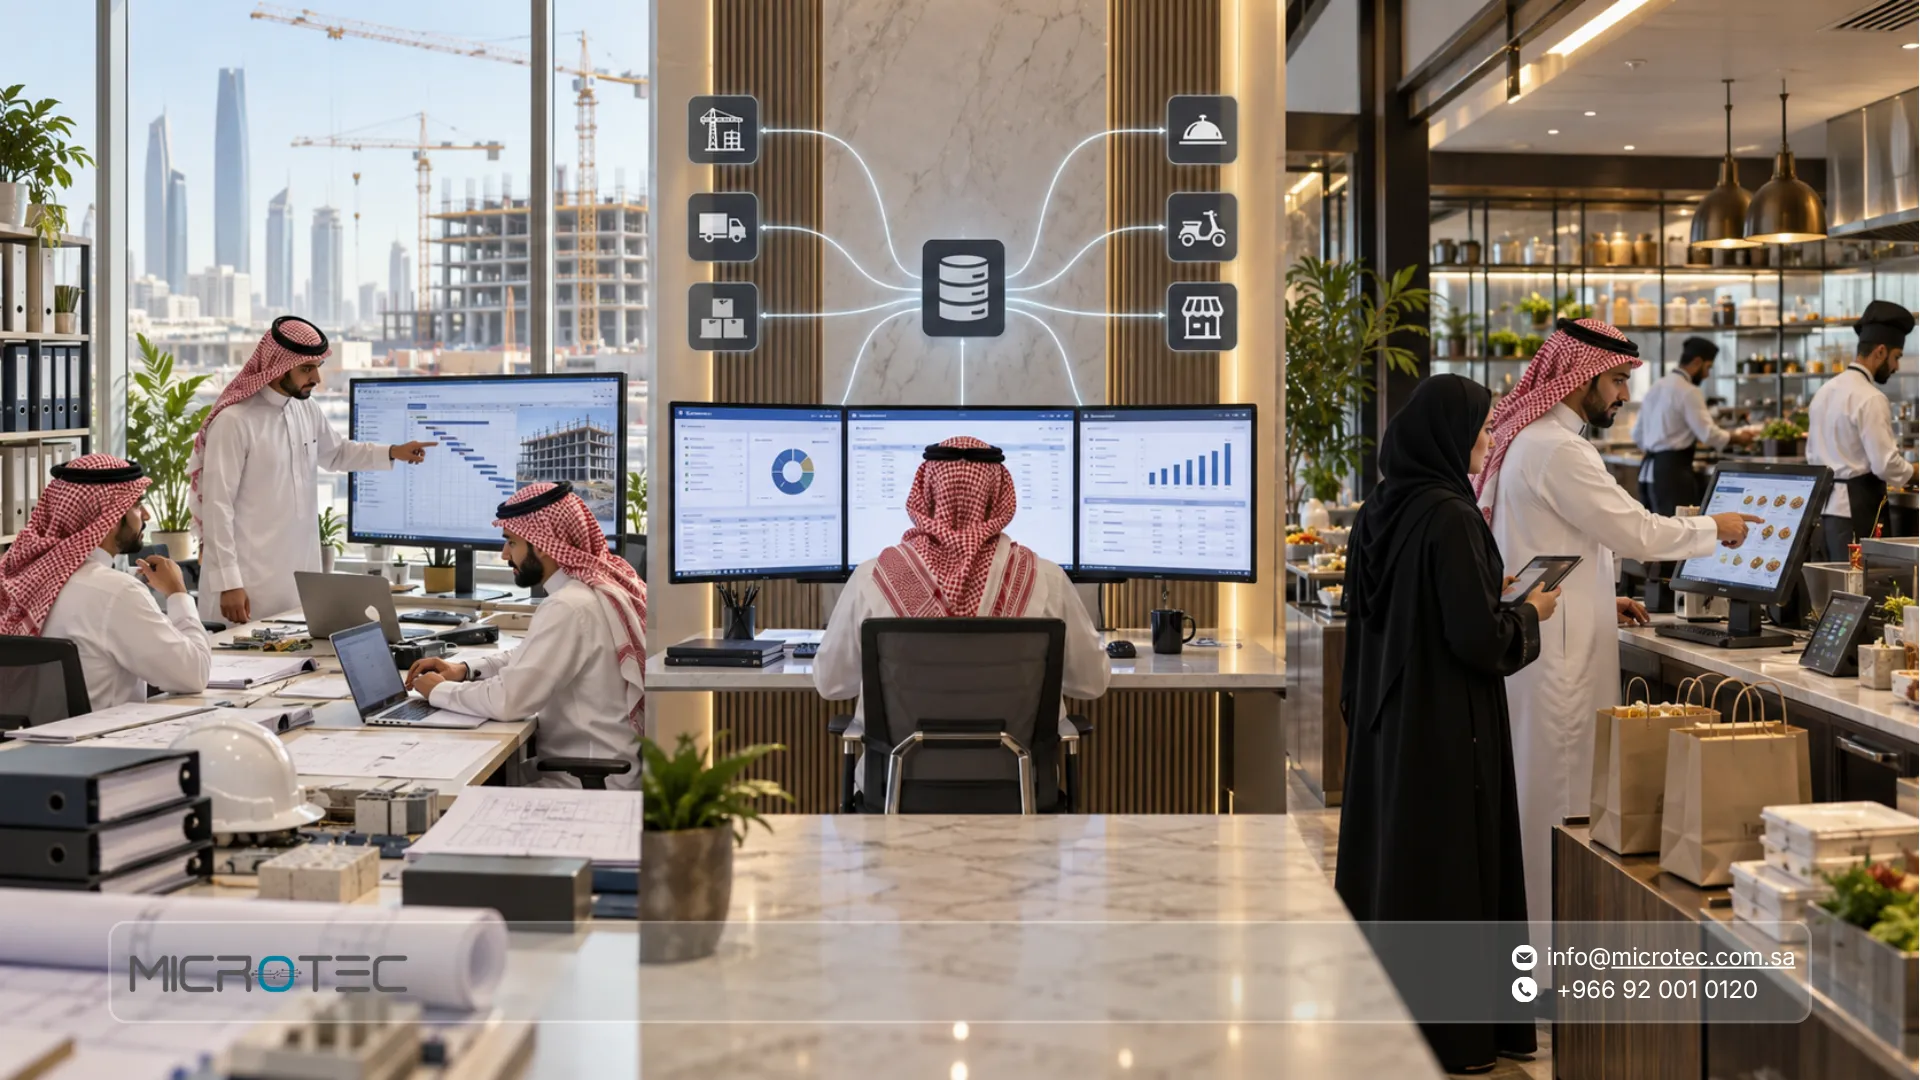
Microtec approaches the two sectors through a shared ERP foundation with different operational tools around it.
For construction and real estate, Microtec’s ERP platform includes project management, cost tracking, purchasing, inventory, and financial management. For restaurants and cafés, O-RED manages orders, payments, and restaurant operations while integrating with ERP for inventory, sales, and cost management.
The objective is not to make restaurant accounting look like project accounting. It is to let each sector generate the right financial data from its own operating cycle.
Microtec vs a Generic Accounting-Only Setup
| Requirement | Microtec environment | Accounting-only setup without operational integration |
| Construction project costs | Project and cost tracking can sit within ERP | Additional project sheets may be needed |
| Purchasing | Purchasing can connect suppliers, inventory, and finance | Supplier invoices may enter finance without a complete operational trail |
| Inventory | Stock can remain connected with related processes | Stock may be maintained in another application |
| Restaurant POS | O-RED handles restaurant orders and payments | Accounting software alone does not normally run the restaurant floor |
| Restaurant inventory | O-RED integrates with ERP for inventory and cost management | Sales and ingredient usage may require later reconciliation |
| Construction reporting | Project costs can be tracked within the ERP structure | General reports may not show project economics clearly |
| Restaurant reporting | Operational sales data feeds the restaurant system | Finance may receive only summarized sales figures |
| Financial data | Operational modules connect with the broader ERP environment | Data may require imports or manual re-entry |
This comparison is about workflow design, not a claim that every general accounting product lacks these capabilities. Some platforms may offer similar integrations, so each system should be tested against the actual operating cycle.
How Connected Data Helps Expose Cost Variances Earlier
Software does not reduce a project’s costs or a restaurant’s food cost by itself. Its value is that it can make the variance visible while management still has time to investigate it.
In construction, project reports may show that labor has already consumed a large part of its budget while physical progress is lower than planned. Material purchases may also exceed the quantity originally budgeted.
In a restaurant, management may see that actual ingredient consumption is higher than the recipe standard or that a menu item’s cost increased after a supplier price change.
Microtec’s ERP specifically lists project cost tracking for contracting and inventory reporting across its broader operational environment, while O-RED integrates restaurant sales with inventory and cost management.
The system does not answer why the difference happened. It gives management the information needed to ask the question before the variance becomes larger.
The Reports That Matter Most in Each Sector
Both businesses still need financial statements, but operational managers require more detailed reports to understand what is driving those statements.
Key Construction Reports
Useful reports can include:
- project cost to date;
- budget vs actual;
- material cost by project;
- labor and equipment cost;
- subcontractor balances;
- progress claims;
- customer collections;
- retention balances;
- committed costs;
- project margin;
- project cash flow;
- estimated cost to complete.
The objective is to see whether the project remains financially healthy before completion.
Key Restaurant Reports
Restaurant management may need:
- daily sales;
- branch sales;
- channel sales;
- sales by menu item;
- recipe cost;
- item margin;
- ingredient movement;
- waste variance;
- cancellations;
- discounts;
- cash differences;
- shift performance;
- delivery-platform receivables;
- supplier purchases;
- low-stock ingredients.
The best report is not necessarily the longest. It is the report that helps management understand where to investigate.
Do Not Use One Accounting Cycle for Two Different Businesses
Construction accounting is built around projects that can remain open for months or years. Restaurant accounting is built around fast, repeated transactions that can begin with an order and end within minutes.
A contractor needs visibility into contracts, project budgets, costs, progress claims, retention, subcontractors, and collections. A restaurant needs visibility into menu items, recipes, ingredient consumption, waste, shifts, payment methods, and sales channels.
The same financial ERP can support both environments, but the operational layer has to reflect the business itself.
Microtec combines its ERP financial and operational modules with O-RED for restaurants and cafés, allowing each business to build the workflow around its actual activity rather than forcing everything through a generic accounting screen.
If you want clearer visibility into project profitability or restaurant food cost, explore Microtec and see how each transaction flows from operations into inventory, cost, and accounting!
FAQs on Construction and Restaurant Accounting
How is percentage of completion calculated?
There is no percentage-of-completion formula that should be applied automatically to every construction contract.
Under IFRS 15, the company must first determine whether the performance obligation is satisfied over time. If it is, an appropriate method is used to measure progress.
A cost-based input method may be appropriate in some circumstances, using costs that properly reflect performance completed to date relative to expected costs. The exact method should reflect the contract, accounting policy, and requirements of IFRS 15.
What is the difference between a progress claim and a tax invoice?
A progress claim generally represents work measured or certified under the project and contractual process. A tax invoice is a tax document subject to invoicing and VAT requirements.
The two can be connected, but they are not the same concept. ZATCA’s contracting-sector VAT guidance specifically addresses tax due dates and invoice timing for the sector.
How do you calculate food cost per dish?
Start with a standard recipe showing the quantity of each ingredient required for the item. Multiply each ingredient quantity by its current cost and add any other direct item-level cost included in the company’s costing method, such as packaging.
That theoretical cost should then be compared with actual ingredient consumption. If the recipe suggests one level of usage but inventory shows another, investigate waste, portion size, spoilage, receiving errors, or recipe accuracy.
Can one accounting system serve construction and restaurants?
The same ERP financial engine can potentially support both sectors, but the operational workflows should differ.
Construction needs project accounting, cost tracking, claims, budgets, and contract-related information. Restaurants need POS, recipes, orders, shifts, ingredient inventory, waste, and daily operational controls.
The stronger approach is an integrated finance platform with operational functionality appropriate to each sector.
What is the most important part of construction accounting?
One of the most important capabilities is seeing profitability by project.
Company-wide profit can hide one poorly performing contract behind another profitable project. Materials, labor, equipment, subcontractors, expenses, claims, and collections therefore need to remain connected to the relevant project.
What is the most important part of restaurant accounting?
A restaurant needs to connect sales with food cost.
Knowing revenue without ingredient consumption, waste, discounts, and commissions makes it difficult to understand the economics of individual menu items.
What VAT rate applies to restaurant sales in Saudi Arabia?
Saudi Arabia currently applies a 15% standard VAT rate to taxable supplies where the standard rate applies. Restaurants need to account for sales and VAT according to the nature of the transaction and the applicable ZATCA requirements.
Is construction retention a loss?
No. Retention does not automatically mean that the contractor has lost the amount.
It is generally an amount withheld under the contract until specified conditions are met. Finance should track it separately from collections and project profit and determine its accounting and tax treatment according to the contract and applicable requirements.